
To all who have served in the U.S. Armed Forces, thank you. The VA home loan is a benefit you’ve earned through your service. If you’re eligible and buying a primary residence, it may be your best mortgage option.
What makes a VA home loan worth a look?
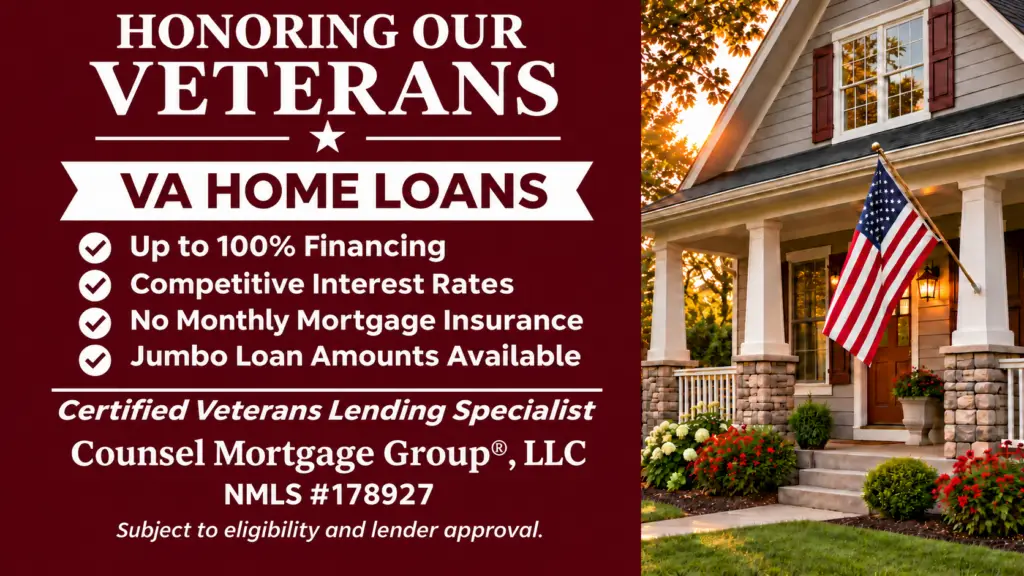
- Up to 100% financing. Eligible buyers may purchase a home with no down payment when the purchase price is at or below the VA appraised value and they qualify for the loan. Closing costs may still apply.
- Competitive interest rates. VA rates are often lower than comparable conventional rates. Comparing the rate, APR, and closing costs side by side helps you see which loan offers better terms for your purchase.
- No monthly mortgage insurance. VA loans don’t require monthly mortgage insurance, even with zero down.
- Jumbo loan amounts are available. With full VA entitlement, the VA doesn’t impose a loan limit. Lender limits and qualification requirements still apply. If you have partial entitlement, a down payment may be required.
- Flexibility in what you buy. You can finance a single-family home, a condo in a VA-approved project, or a property with up to four units if you’ll live in one of them.
- A benefit you can use again. Depending on your available entitlement, you may be able to use your VA loan benefit for a future purchase. VA loans also have no prepayment penalty.
A one-time VA funding fee generally applies unless you qualify for an exemption, such as receiving VA compensation for a service-connected disability.
I am a Certified Veterans Lending Specialist (CVLS). Whether you’re buying your first home or planning your next move, I can help you review your VA entitlement and compare your monthly payment and cash needed at closing with a VA loan and a conventional loan.
